


Management Summary
How would the new SEC climate regulations impact the bond?
While the proposed rules are for public companies, municipal bond issuers like PHA and borrowers should still pay attention to the potential impact on climate-related disclosures. For issuers and borrowers who already have a practice of disclosing climate-related risks in their offering documents, the SEC’s proposed rules provide more detailed and focused considerations for developing their existing climate-related risk disclosure. Issuers and borrowers should be careful that their climate-related risk disclosures are accurate and comprehensive. According to SEC Rule 10b-5 it is unlawful for issuers or borrowers in their public disclosures:
“to make any untrue statement of a material fact or to omit to state a material fact necessary in order to make the statements made, in the light of the circumstances under which they were made, not misleading.” SEC
This means that issuers and borrowers must disclose risks that are material to the decision-making of a reasonable investor. This requires collaboration with a disclosure counsel, underwriters and experts to give the complete climate-related picture, including risks and opportunities.
While issuers and borrowers are only obligated to provide information in annual reports that they have contractually agreed to provide at the time of issuance of the debt instrument (often in the form of a continuing disclosure agreement or continuing disclosure certificate), there may be a push by ESG investors for issuers and borrowers to start including updates to their climate-risk disclosure as part of their annual reporting obligations going forward. Annual updates regarding climate-related risks are relevant to the secondary market – especially to ESG investors – who are buying and selling securities long after the publication of the related offering document.
How would PHA make payments if it were to close for 3 to 6 months because of a severe hurricane?
As the port prioritizes expansion with Project 11, there is concern about whether or not the coastal protection system will be finished to protect the port against the next major hurricane. Generally, Texas experiences hurricanes every three years, with a major hurricane every decade. The frequency and magnitude of hurricanes is projected to increase with climate change.
However, as the ECP program lacks a liquidity facility, please note maturities can extend up to 270 days, affording PHA additional time to retire outstanding notes.
The PHA can adjust ad valorem taxes, subject to Harris County voter approval, to fund its unlimited-tax bonds. Property tax revenues generated from the regular tax levy available by PHA in 2022 amounted to $45 million in fiscal, 6.4% of total revenue received by PHA. Revenues per capita vs. expenditures per capita have grown 2017-2021 and were last reported to be $119.70 and $74.43 for a difference of $45.27 respectively. At the same time, Ad Valorem taxes per $100 valuation also declined from $0.01256 to $0.00872 respectively over the same period of time (see Figure 1).
But as demonstrated in Figure 1, right image, the difference for PHA between its revenues and expenditures over the past five years, is equal to a single “three-months” of revenue. If PHA were shut down for 3 months, the firm would need to possibly obtain a short-term loan to fund its expenditures, assuming revenues were zero.
How much will it cost PHA per year to finance the bond?
The Port of Houston Authority has issued a series of municipal bonds called the Texas First Lien Revenue Bonds, series 2023, in order to fund the cost of the design, construction, property acquisition, and equipment of the Houston Ship Channel Expansion Channel Improvement Project, referred to as Project 11.
In this paper, the bonds are analyzed from several angles, including regulatory, financial, regulatory perspectives.
What impact does the bond have on future borrowing capacity?
The rate covenant requires net revenues to provide at least 125% debt service coverage (DSC), per the resolution, on all revenue bonds outstanding (first, second, and third lien obligations combined); however, management has a debt policy to target 300% DSC on first-lien revenue bonds.
An additional bonds test is also in effect based on a historical test of:
150% maximum annual DSC on all outstanding first lien obligations.
135% maximum annual DSC on all outstanding first lien obligations and second lien obligations.
125% maximum annual DSC on all outstanding first lien obligations, second lien obligations, and third lien obligations.
The bonds do not have a debt service reserve account, given net revenues are expected to exceed 300% DSC per the resolution.
However, as the ECP program lacks a liquidity facility, please note maturities can extend up to 270 days, affording PHA additional time to retire outstanding notes.
The PHA can adjust ad valorem taxes, subject to Harris County voter approval, to fund its unlimited-tax bonds. Property tax revenues generated from the regular tax levy available by PHA in 2022 amounted to $45 million in fiscal, 6.4% of total revenue received by PHA. Revenues per capita vs. expenditures per capita have grown 2017-2021 and were last reported to be $119.70 and $74.43 for a difference of $45.27 respectively. At the same time, Ad Valorem taxes per $100 valuation also declined from $0.01256 to $0.00872 respectively over the same period of time. But none of these scenarios above address climate risks.
How do the infrastructure investments funded by the bond, e.g., Project 11, improve PHA’s financial performance, and does the bond cost represent a good investment?
The bonds are backed by revenue from the issuing entity, in this case, the Port of Houston. Revenue bonds were chosen instead of general obligation bonds, which are largely backed by the taxing authority of the entity. Property tax revenues generated from the regular tax levy available by PHA in 2022 amounted to $45 million in fiscal, 6.4% of total revenue received by PHA.
The claimed aim of a wider and safer channel is to maintain two-way traffic for the benefit to all users of the bay while maintaining the economic and safety priorities of the channel.
When complete, Project 11 is expected to reduce vessel-related emissions by between 3% and 7% annually.
Port of Houston Authority of Harris County, Texas First Lien Revenue Bonds, series 2023
The Port of Houston Authority (“PHA”) of Harris County, Texas First Lien Revenue Bonds (“bonds”), series 2023, for $393,585,000, are secured by net revenues of the port facilities and include gross revenues minus cost of operations and maintenance (see Table 1).
Table 1: Issue Description, Bid-Ask Spreads, and Information
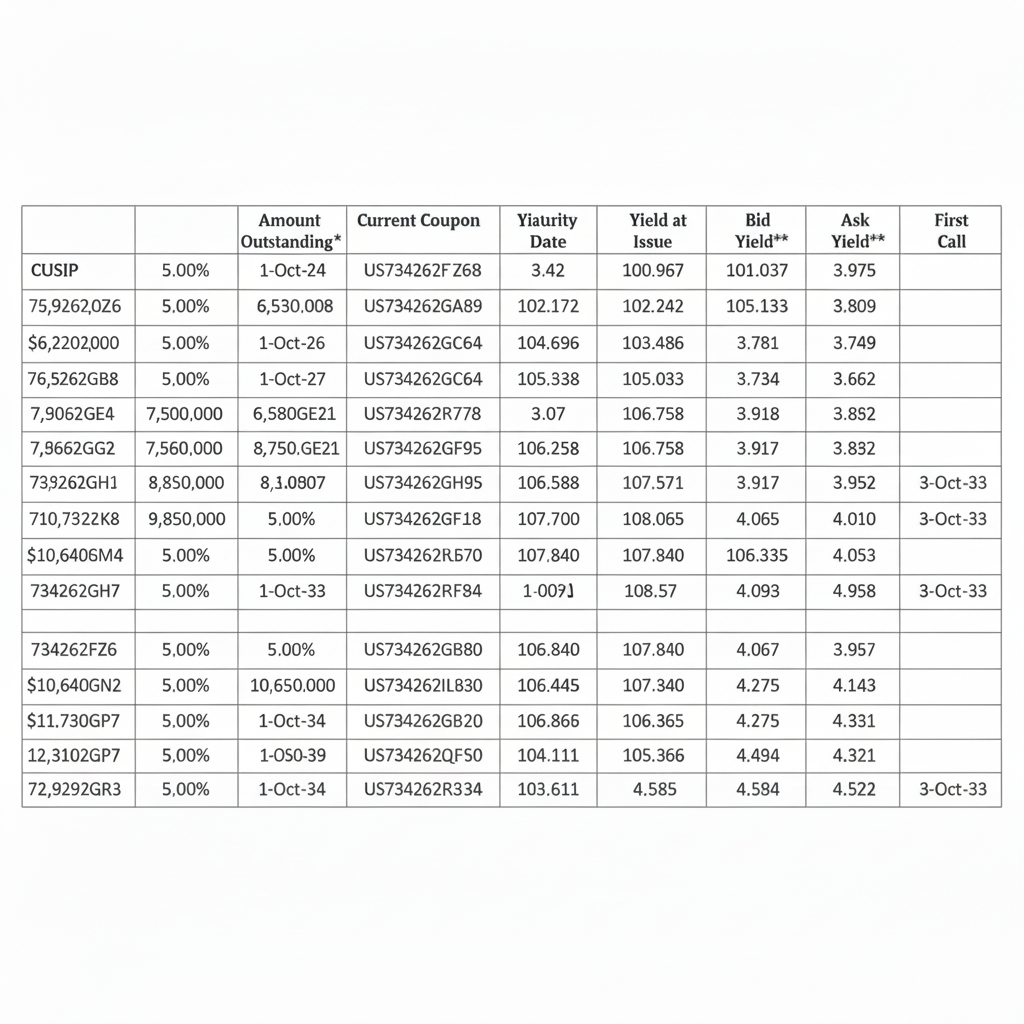
The bond was sold into the primary markets and started trading in the secondary market in Q3 2023. It is a fixed plain vanilla bond rated AA+ (S&P) and Aa3 (Moody’s) with a Stable outlook (S&P) (see Table 2).
Table 2: Issuer Description
| ISSUE DESCRIPTION | INFORMATION | ISSUE DESCRIPTION 2 | ISSUE DESCRIPTION 3 |
| Type | Fixed Plain Vanilla | Min. Denomination/ Increment | 5,000/5,000 |
| Day Count | 30/360 ISDA | Offering Type | Negotiated |
| Next Pay Date | 1-Apr-24 | Bond Form | Book Entry |
| S&P Long-term Issue Credit Rating | AA+ (24-Jul-2023) | Financials Filed | No |
| Moody’s Long-term Issue Credit Rating | Aa3 (24-Jul-2023) | Bank Qualified | No |
| Moody’s Long-term Underlying Rating | Aa3 (24-Jul-2023) | Paying Agent | Zions Bank |
| Green Bond | No | Registrar | Zions Bank |
| Underwriter/ Manager | Morgan Stanley | Bond Counsel | Greenberg Traurig |
| Member of Underwriting | Blaylock Van | Tender Agent | – |
| Hilltop Securities | Hilltop Securities | Escrow Agent | – |
| Loop Capital Markets | Loop Capital Markets | Financial Advisor | PFM Financial |
| Prospectus Available | Yes | Transfer Agent | – |
| Series Number | 2023 | Trustee | – |
| Default Status | – | Remarketing Agent | – |
| Project Name | – | Mortgage Insurance | – |
| Private Placement | No | Enhancement Type | – |
| Deposit Type | Depository Trust Co | LOC Type | – |
| Purpose | Seaports/ Terminals | LOC Expiration | – |
| Calculation Type | Corporate Bond |
Port of Houston Economic Impact
The PHA is a key economic resource for the U.S., the regions, and the state of Texas:
5th ranked U.S. container port by total twenty-foot equivalent unit (TEUs). The TEUs are The twenty-foot equivalent unit is an inexact unit of cargo capacity, often used for container ships and container ports. It is based on the volume of a 20-foot-long intermodal container, a standard-sized metal box which can be easily transferred between different modes of transportation, such as ships, trains, and trucks.
Largest Gulf Coast container port, handling 73% of U.S. Gulf Coast container traffic.
Largest Texas port with 97% market share in containers.
1st ranked U.S. port in foreign waterborne tonnage – 220.5 million short tons (2022).
1st ranked U.S. port in total foreign and domestic waterborne tonnage – 266 million short tons (2021).
2nd ranked U.S. port in terms of total foreign cargo value ($240.1 billion) 2022.
150-plus private industrial companies.
A 25-mile-long complex of diversified public and private facilities including the nation’s largest petrochemical complex (second largest in the world) (see Appendix for more context).
The largest facility in the U.S. for raw plastic resin export.
Access to three class-1 railroads (BNSF, Union Pacific, TexMex/Kansas City Southern).
The nation’s sixth-largest container terminal complex (and the largest on the Gulf Coast).
The PHA is an autonomous governmental entity authorized by the Texas Legislature in 1927 to oversee and manage the Port of Houston and the Houston Ship Channel. The Port Authority also owns and maintains the public terminals within the Port of Houston, including the nation’s largest break-bulk terminal (for large, individually loaded cargo items) as well as container terminals at Bayport and Barbours Cut, which combined represent the largest container terminal on the U.S. Gulf Coast.
The PHA is a political subdivision of Texas, having boundaries generally coterminous with Harris County.
The bonds will fund the cost of the design, construction, property acquisition, and equipment of the Houston Ship Channel Expansion Channel Improvement Project and pay costs associated with issuance, including for Project 11. Because the expansion channel program is not funded via a liquidity facility, it can extend its maturities for an additional six months to roll over or retire notes outstanding.
The PHA can adjust ad valorem taxes, subject to Harris County voter approval, to fund its unlimited-tax bonds. Property tax revenues generated from the regular tax levy available by PHA in 2022 amounted to $45 million in fiscal, 6.4% of total revenue received by PHA. Revenues per capita vs. expenditures per capita have grown 2017-2021 and were last reported to be $119.70 and $74.43 for a difference of $45.27 respectively. At the same time, Ad Valorem taxes per $100 valuation also declined from $0.01256 to $0.00872 respectively over the same period of time (see Figure 1).

According to management, in fiscal 2022, approximately 82% of revenue is derived from container terminals while only 64% of cargo tonnage is from containerized traffic. Despite historical container terminal revenue growth of 13.8% on a five-year compounded annual growth rate (CAGR), management forecasts a 2.9% CAGR in container revenue from 2023 through 2027.
Yet, while PHA’s revenue has steadily increased since 2016, its long-term debt has also increased when PHA issued the Series 2021 Revenue Bonds, before PHA issued its 2023 series bonds (see Figure 2).

Table 3: Panamex vs. Neo-Panamex Vessels
| Panamex | Neo-Panamex | |
| Maximum Length | 965 feet | 1201 feet |
| Maximum Width | 106 feet | 161 feet |
| Container capacity | 5,000 TEUs | (up to) 15,000TEUs |
Project 11
PHA stated commitment is to expand and improve PHA facilities, much in response to the expansion of the Panama Canal in 2016, which improved trade between the Pacifica Rim and the Western Hemisphere by allowing the Panama Canal to allow for “Neo-Panamax class” (15,000 TEUs nominal capacity) vessels (see Table 3).
A portion of the use of proceeds from the sale of the securities will be to fund Project 11. Project 11 is the Houston Ship Channel expansion project that includes an array of dredging and infrastructure projects aimed at easing traffic throughout the port. As the nation’s largest importer and exporter of petroleum and petroleum related products, the port has seen a great increase in demand This is evidenced by growth in U.S. energy exports, namely that demand for crude oil is twenty times higher than it was a decade ago. According to the Houston chamber of commerce, the channel adds more than $800 billion to the U.S. economy.
To finance Project 11, PHA issued $393.6 million in federally tax-exempt revenue bonds. Revenue bonds are backed by revenue from the issuing entity, in this case, the Port of Houston. Revenue bonds were chosen instead of general obligation bonds, which are largely backed by the taxing authority of the entity. Maturing between 2024 and 2053, the bonds will yield between 3.06% and 4.25% with a coupon rate of 5%. The securities are rated Aa3 by Moody’s Investors Service and AA+ by S&P Global Ratings. Morgan Stanley & Co LLC played a prominent role as the lead underwriter in the bond issuance, acquiring the bonds for a total of $426 million. This amount included an initial issue premium of $34 million (see Table 2).
Project 11 will widen the channel by 170 feet along its Galveston Bay reach, from 530 feet to 700 feet. It also will widen other upstream segments and deepen downstream segments to 46.5 feet. Lastly, it will make safety and other efficiency improvements (see Figure 3).

The Army of Corps of Engineers confirmed the following tasks as part of the Houston Ship Channel (HSC) Expansion Channel Improvement Project (Project 11):
Four bend casings on the main HSC channel with associated relocation of barge lanes.
Widening of the HSC main channel between Bolivar Roads and BCC from the existing 530-foot width to 700 feet with associated relocation of barge lanes.
Widening of the BSC on the north side of the channel to 455 feet.
Widening of the BCC on the north side of the channel to 455 feet.
Widening of the BCC flare on the north and south side to create an 1,800-foot diameter turning basin.
Deepening of the HSC main channel from Boggy Bayou to the Hunting Turning Basin up to 46.5 feet.
Widening the HSC main channel from Boggy Bayou to Greens Bayou from the existing 400-foot-wide channel up to 530 feet.
Deepening of the KSC main channel from Sims Bayou to the 1-610 Bridge up to 41.5 feet; Deepening of the HSC main channel from the 1-6 10 Bridge to the Main Turning Basin up to 41.5 feet.
Improving the Brady Island Turning Basin to a 900-foot diameter.
Inclusion of the Greens Bayou Channel, a 1.6-mile-long channel with a combination of 41.5-foot depth and 16.5-foot depth, into the federal project.
Inclusion of the Jacintoport Channel, measuring 0.76-mile long by 41.5 feet deep, into the federal project.
Construction of the recommended plan involves the dredging of approximately 350 million cubic yards of material for both new work and additional operation and maintenance. Material will be removed using multiple types of dredge equipment using mechanical clamshell, hydraulic hopper, and hydraulic cutter suction. Proposed placement sites include upland disposal, marsh island creation, open water placement, and placement in existing ocean dredged material disposal sites, as outlined in the Dredged Material Management Plan.
To compensate for the unavoidable adverse effects on various significant habitat types, the project includes mitigation of approximately 377 acres of oyster habitat and 72 acres of wetland. Mitigation for wetland impacts would occur through purchase of wetland mitigation bank credits at a bank approved by the U.S. Army Corps of Engineers, Galveston District. Monitoring to determine the success of the mitigation is expected to last three years, but no more than 10 years.
To mitigate the anticipated air quality impacts from implementing the Recommended Plan, Discrete Emission Reduction Credits would be purchased through an existing emissions bank as outlined in the mitigation plan. This mitigation plan has been approved by the Texas Department of Environmental Quality
The rate covenant requires net revenues to provide at least 125% debt service coverage (DSC), per the resolution, on all revenue bonds outstanding (first, second, and third lien obligations combined); however, management has a debt policy to target 300% DSC on first-lien revenue bonds.
An additional bonds test is also in effect based on a historical test of:
150% maximum annual DSC on all outstanding first lien obligations.
135% maximum annual DSC on all outstanding first lien obligations and second lien obligations.
125% maximum annual DSC on all outstanding first lien obligations, second lien obligations, and third lien obligations.
The bonds do not have a debt service reserve account, given net revenues are expected to exceed 300% DSC per the resolution.
The unlimited-tax refunding bonds are payable from the receipts of an annual ad valorem tax levied by the Harris County Commissioners Court, without limit as to rate or amount, on all taxable property within Harris County.
PHA and Climate Risk
PHA and Project 11 lack any disclosure of climate risk in any material way on their website, associated with the Project 11 documents reviewed, or in the bonds’ prospectus.
In terms of emerging risks from climatic events that are attributable to an accelerated change in the global climate, as well as adverse regional weather conditions, the financial statements of the Port of Houston Authority fail to provide sufficient information about their appropriate accounting.
As of the day of submission of this paper and despite the fact that no disclosure requirements for PHA exist, a timely consideration of these risks will ultimately lead to long term profitability of the Port. As U.S. Government data demonstrates, local climate change is directly impacting PHA.
By 2053, the maturity date of the final bond series payment, high tide flooding days in Houston are forecast to range from 110 days per year to 135 days per year depending if globally we are on a lower or higher emissions pathway (see Figure 4).

An analysis by the National Oceanic and Atmospheric Administration and Texas Tribune shows a significant rise of monthly average air temperatures in the area of Houston, including record highs accumulating concerningly in the past decade.
Similarly, water surface temperatures have risen in the Gulf of Mexico, and in particular in the region of Galveston Bay. Higher water surface temperature favors both the formation of category 3 to 5 hurricanes and their frequency.
Given the geographical location, the Port’s facilities and infrastructure, including the channel leading up to the Port, are particularly vulnerable to severe weather events. Therefore, it is strongly recommended to the Port of Houston Authority to employ up-to-date climate models that allow for comprehensive financial accounting, including operational risk, which is a non-financial risk category.
It is acknowledged that the Port of Houston Authority has developed a Sustainability Action Plan (SAT), that considers resilience “when faced with acute shocks and chronic stresses”. It is, however, concerning when channel expansion plans utilize models for wind conditions that date back to 1992, while much more information on winds is nowadays available.
Such information can be efficiently incorporated into financial modeling, for example, following the approaches developed and mandated by the Task Force for Climate-Related Disclosures (TCFD).
Their approach differentiates between physical risk and transition risk. Transition risks arise from the economic transformation and any dislocation needed to drastically reduce, and eventually eliminate, net greenhouse gas emissions to reach net-zero emissions. Physical risks are the physical effects from changing weather patterns that result from climate change, which are further subdivided into chronic and acute physical risks.
Acute risks include weather related or impacted events, such as hurricanes, whereas chronic risks include gradual risks, such as sea-level rise and increasing average temperatures.
Climate-related financial risks impact financial statements, drive asset and liability repricing, impact loan defaults, and supply chain revenue / cost of goods sold (see Figure 5). This is aligned with scientific guidance from the IPCC and the goals of the Paris Agreement to keep emissions “well below 2º Celsius above pre-industrial levels” while pursuing efforts to limit the rise to 1.5º Celsius.
The Port of Houston and Project 11 lack any disclosure of climate risks, in particular acute physical risks. It is unclear how severe weather events, and their destructive potential are considered and accounted for in short-, medium, and long-term financial planning models. These risks ought to be priced and capital needs to be reserved to ensure financial liquidity in order to be able to meet short-term obligations. Appropriate insurance policies are not in place as far as information is provided to capital market data providers, such as Bloomberg and Refinitiv.

The U.S. government has a 170-year record of tracking tropical storms and hurricanes that have passed through and next to Harris County, where PHA is located. Since 1854, 76 significant storms have passed over and next to Harris County (see Figure 6, with a complete list in the Appendix: Table 5).
The U.S. government records 11 major hurricanes, Category 3 to Category 5, with direct hit on Harris County (or next to) from 1900 to present. This is one direct hit every 11 years.
The bonds’ series matures from 2024 to 2053, which is a period of 30 years. Consequently, we can forecast that est. three major hurricanes may directly hit or pass nearby Harris County in the next 30 years.

The Sea, Lake and Overland Surges from Hurricanes (SLOSH) model developed by the National Weather Service (NWS) estimates storm surge heights resulting from historical, hypothetical, or predicted hurricanes. It takes into account atmospheric pressure, size, forward speed, and track data. These parameters are used to create a model of the wind field which drives the storm surge.
The SLOSH model consists of a set of physics equations which are applied to a specific locale’s shoreline, incorporating the unique bay and river configurations, water depths, bridges, roads, levees and other physical features.
The NHC SLOSH Model (Storm Surge) layer with the red fading to blue, the regions are as follows:
The metric shown is inundation height (ft):
Blue coloring = up to 3 feet above ground.
Yellow coloring = greater than 3 feet above ground.
Orange coloring = greater than 6 feet above ground.
Red coloring = greater than 9 feet above ground.
Black hatched = leveed area so consult local officials for flood risk.


When assessing Project 11’s project area, it is clear that when only looking at historical records that major hurricanes (Category 3, 4, and 5) hit or pass nearby Houston every 11 years (1900 to 2022) and that Houston specifically has been hit by eight hurricanes and storms that caused more than one billion in damages in the last 40 years.
Given this historical data, and not including forecasts that suggest hurricane’s intensity, frequency, and size may increase due to climate change, it is clear that Project 11 and its surrounding area face real and material risks from hurricanes, much less climate change, neither of which are addressed in the bonds’ prospectus.
Furthermore, it is also clear that Project 11 faces immediate risks from storm surge according to U.S. government forecasts (see Figure 7, Figure 8, Figure 9, Figure 10, and Figure 11).
Climate Regulations
At the time of submission of this white paper, the United States Securities and Exchange Commission (SEC) has not published rules for Climate Change Disclosure. However, development of the proposed set of rules, titled “The Enhancement and Standardization of Climate-Related Disclosures for Investors”, is in the final stage (Office of Information and Regulatory Affairs 2023).
In 2022, Responsible Alpha co-wrote a submission to the SEC describing in detail the need from the SEC to incorporate risks to communities from climate change as a material risk, as suggested by the TCFD, to be reported in securities’ filings. The submissions were resubmitted by 123 NGOs, environmental, and social justice organizations in response to the SEC’s proposal for “The Enhancement and Standardization of Climate-Related Disclosures for Investors”.
In response, the SEC released proposed rules requiring public companies to provide certain climate-related risks and opportunities including greenhouse gas emissions and any risks that could have material impact on operations, business, and financial condition.
A registration statement for public companies is similar to an offering document, official statement or offering memorandum in the municipal context for issuers and borrowers. Issuers and borrowers often have a practice of disclosing risk factors relevant to the security for and sources of payment of the securities being issued and, in many cases, risks relevant to an issuer’s or borrower’s operations and finances. It is not uncommon to see risk factors in an offering document for municipal securities relating to climate change, including global warming, GHG emissions, or climate-related events like earthquakes, wildfire, floods, and tsunami, as and if relevant.
If the SEC rules were amended, a public company would have to disclose in its registration statements and annual reports the following climate-related risks:
Anticipated short, medium or long-term material impacts of climate-related risks on business and consolidated financial statements.
Past, present and future impacts of climate-related risks on strategy, business model, and outlook.
The public company’s processes for identifying, assessing, and managing climate-related risks and whether any such processes are integrated into the public company’s overall risk management system.
The impact of severe weather events (and other physical risks) and transition activities (including risks) to be included on consolidated financial statements and expenditures and for the financial estimates and assumptions of these risks to be disclosed.
The impact of transition activities (including risks) to be included on consolidated financial statements.
The public company would also require its board and corresponding management to oversee and govern climate-related risks. Similarly, the public company would need to disclose their transition plan (if applicable) and any climate-related goals or interim targets.
Lastly, the public company would be required to show greenhouse gas emissions metrics to investors which would help with the assessment of risks, with possible third-party verification requirements. The public company would also be able to disclose climate-related opportunities to the public.
While the proposed rules are for public companies, municipal bond issuers like PHA and borrowers should still pay attention to the potential impact on climate-related disclosures. For issuers and borrowers who already have a practice of disclosing climate-related risks in their offering documents, the SEC’s proposed rules provide more detailed and focused considerations for developing their existing climate-related risk disclosure. Issuers and borrowers should be careful that their climate-related risk disclosures are accurate and comprehensive. According to SEC Rule 10b-5 it is unlawful for issuers or borrowers in their public disclosures:
“to make any untrue statement of a material fact or to omit to state a material fact necessary in order to make the statements made, in the light of the circumstances under which they were made, not misleading.” SEC.
This means that issuers and borrowers must disclose risks that are material to the decision-making of a reasonable investor. This requires collaboration with a disclosure counsel, underwriters and experts to give the complete climate-related picture, including risks and opportunities.
While issuers and borrowers are only obligated to provide information in annual reports that they have contractually agreed to provide at the time of issuance of the debt instrument (often in the form of a continuing disclosure agreement or continuing disclosure certificate), there may be a push by ESG investors for issuers and borrowers to start including updates to their climate-risk disclosure as part of their annual reporting obligations going forward. Annual updates regarding climate-related risks are relevant to the secondary market – especially to ESG investors – who are buying and selling securities long after the publication of the related offering document.
Lastly, issuers and borrowers generally prepare financial statements within the guidelines of the Governmental Accounting Standards Board (GASB). While climate-related metrics are not currently required, this will need to be monitored in the future with the potential for the quantification of climate-related costs.
Implications on PHA Bonds
As it stands, PHA’s First Lien Revenue Bonds, Series 2021 Official Statement includes disclosures of risks for “climate change and sea level rise,” “weather-related catastrophe,” “other environmental and related risks,” and “prolonged channel closure.”
For example, the “weather-related catastrophe” disclosure is as follows:
“The Port Facilities are located on the Gulf Coast of the United States. The Gulf Coast is an area that has in the past been periodically susceptible to damaging storms. The risk of hurricanes, tropical storms, winter storms or other major weather events affecting the Port Facilities and ship channels and interrupting the operations of the Authority is a risk over which the Authority has little or no control. To the extent that the Port Facilities are damaged, or the Authority’s operations are interrupted for any material period of time or cargo is directed to other ports due to hurricane or other weather-related catastrophe, such damage or interruption could reduce the amount of Net Revenues available to the Authority, which would have an adverse impact on the Authority’s ability to satisfy its debt service obligations on the Bonds.”
When reviewed through the lens of the SEC’s proposed rules, the disclosure fails to anticipate short, medium or long-term material impacts of weather-related catastrophe on business and consolidated financial statements; fails to mention past, present and future impacts of weather-related catastrophe on strategy, business model and outlooks; fails to disclose the process of identifying, assessing, and managing weather related catastrophe; fails to disclose the financial estimates and assumptions of the impact of weather-related catastrophe; finally fails to disclose the impact of transition activities, in this case, adaptive infrastructure and associated protections against weather-related catastrophe. In short, a failure across the board in every disclosure-related category.
A lack of responsibility is evident in the “weather-related catastrophe” disclosure noting it’s a risk “over which the Authority has little or no control.” Similarly, the “prolonged channel closure” disclosure states “Such a closure could occur as a result of an oil spill, chemical spill, or spill of other harmful or hazardous materials in the Channel, a ship collision, a weather-related event or other channel obstruction. The U.S. Coast Guard makes the determinations on Channel closures and re-openings.” While both risks could negatively impact PHA’s ability to satisfy its debt obligations, no solutions nor protections are listed, and similarly, no disclosure of cost or probability estimates around these risks. In the “climate change and sea level rise” disclosure, PHA reveals that “Port operations and infrastructure are vulnerable to effects of sea level rise, extreme climate conditions, and extreme weather events, and significant capital investments may need to be made to address these vulnerabilities.” However, what the “significant capital investments may be, how much they will cost, and when they will be operationalized remains a mystery.
Scenario Analysis
In 2023, we now expect an above-average hurricane season in 2023 given record-breaking North Atlantic Sea Surface Temperatures (SSTs). Warmer SSTs provide the fuel that supports storm intensification and are expected to dominate other factors. The revised forecasts highlight Florida, Louisiana, and Texas as areas of elevated risk.
The strength of the 2023 hurricane season will be determined by a trade-off between historically warm SSTs and El Niño winds. Typically, an El Niño is associated with weaker hurricanes while warmer SST’s is associated with stronger hurricanes. It is forecast that the warmer SST effect to dominate in 2023, resulting in a stronger-than-average season.
For the Hurricane season in 2023, it is predicted that there will be 18 named storms, which includes 4 major hurricanes. Storm damage is ultimately a function of a number of factors including whether they make landfall, storm strength, location of impact, duration of impact, and storm surge size. From 2010 to 2022, storms with an Accumulated Cyclone Energy (ACE) around 160 have generated storm costs ranging from $0 to $90 billion.

Recap of Past Events: 1989 – 2022
As a major port, enabling the export and import of over 200 million short tons annually, even short-term closure of the Port of Houston can have devastating impacts on local and global economies. According to one study, a week-long closure of the Port of Houston can accumulate financial losses up to $2.5 billion.
While the Port of Houston narrowly escaped the impacts of Hurricane Ida in 2021, a storm of that magnitude with its 15-foot storm surge and 150 mph winds, could have bulldozed the Port, industrial facilities, and residential homes, and left Houston without power for weeks.
NOAA’s Nation Weather Center for Environmental Information recorded eight hurricanes and storms that totaled more than one billion in damages as adjusted for a 2016-dollar value between the years of 1980 to 2022.
In 2017, category 4 Hurricane Harvey caused a week-long closure, with a total of two weeks of direct impact and 3-5 years of related reconstruction. Over 150,000 homes in Harris County were damaged or destroyed, resulting in $125 billion in damage along the Gulf Coast of Texas. Hurricane Harvey was classified as a 1000-year, unprecedented storm in the history of North America, resulting in over 40 inches of rain in many parts of Harris County. While the port was able to open after the first week of closure, direct and adjacent hurricane impacts like shoaling and flooded roadways restricted access to port services, slowing the return to business as usual.
In 2016 the so-called Tax Day Floods ($2.8 billion in damages) caused by trans-state thunderstorms dropped 17 inches of rain over Houston and surrounding suburbs, necessitating high-water rescues.
In 2015 so-called Memorial Day Floods ($2.6 billion in damages) caused by slow-moving storms brought torrential rains and flooding to Houston, flooding the city and leaving death and destruction in its wake.
In 2008 category 2 Hurricane Ike ($34.8 billion in damages, the largest storm by size to enter the Gulf of Mexico) hit Galveston, breaching the seawall and destroying the island, damaging Houston and associated electrical infrastructure, and causing port closure.
In 2005, Hurricane Rita ($23.9 billion in damages) hit Houston, causing widespread evacuations but leaving minimal damage.
In 2003 Category 3 Hurricane Alicia ($7.5 billion in damages) hit Galveston and Houston with 115 mph winds and an almost 12-foot storm surge, damaging the surrounding area and causing 21 deaths.
In 2001 Tropical Storm Allison ($11.9 billion in damages) hit Galveston and Houston, causing 30-40 inches of major flooding.
In 1994 the so-called Southeast Texas Floods ($1.7 billion in damages) hit the Gulf of Mexico with four days of thunderstorms and 8-28 inches of torrential rainfall, damaging homes and infrastructure in Galveston and Houston and leading to over 20 deaths.
Future Climate-Related & Financial Risks
The Port of Houston is exposed to both acute and chronic physical and financial risks. A recent Oxford study found that Houston is one of the top 5 at-risk ports globally, suffering from combined risks of cyclone wind, pluvial flooding, and fluvial flooding. Compared to the $123.4 million per year average related risk for high income countries, the Port of Houston’s related risk is well above at $169.0 million per year.
According to Moody’s, cargo dwell times, or how long a cargo waits in port, are a major concern in severe weather events. The longer a cargo remains at port, the more likely it is to be exposed to wind, rain and floodwater. As of 2017 the average daily risk for cargo at the Port of Houston amassed to $7.6 billion.
As the port prioritizes expansion with Project 11, there is concern about whether or not the coastal protection system will be finished to protect the port against the next major hurricane. Generally, Texas experiences hurricanes every three years, with a major hurricane every decade. The frequency and magnitude of hurricanes is projected to increase with climate change.
Financial Analysis
The revenue bonds are backed by the net earnings of the port facilities, calculated as gross revenue minus operational costs. The terms of the bonds are viewed as having a neutral impact on credit. Net earnings are required to cover debt service by at least 1.25 times for all outstanding revenue bonds. However, the port management aims for 3 times coverage for specific bonds. There’s also a test to ensure sufficient coverage for additional bonds, but given the expected surplus, there’s no need for a debt service reserve account.
The unlimited-tax refunding bonds will be funded through an annual property tax levied by the Harris County Commissioners Court. This tax has no fixed limit on rate or amount. The ECP program’s rating is linked to PHA’s long-term, first-lien revenue bond rating, indicating PHA’s ability to use revenue bonds to retire commercial paper notes. PHA is assessed as having low market risk due to its strong borrowing history and transparency. However, as the ECP program lacks a liquidity facility, note maturities can extend up to 270 days, affording PHA additional time to retire outstanding notes.
The series 2023 bonds will cover the expenses for the Houston Ship Channel Expansion Channel Improvement Project, including design, construction, property acquisition, equipment, and issuance costs.
Sensitivity Analysis: Shocked Yield Scenario
In this chapter, the sensitivity of the bonds to changes in interest rates is analyzed. The bonds are priced at issue based on at the time current interest rates and forward rates. Generally, the yield of a bond is a composite of interest rate, and accounts for additional factors, such as inflation, credit risk of the issuer, and federal monetary policies. Changes in one of these factors leads inherently to a change in the net price of the bond.
Table 4 shows this effect assuming the yield increases by 200 basis points (bp) or 2%.
Table 4: This table present the effects on the next price of the bond series in a +200bp nominal yield scenario. Source: Refinitiv
| CUSIP | Amount Outstanding* | Current Coupon | Maturity Date | Yield at Issue | Net Price at Issue | Shocked Scenario: Yield | Shocked Scenario: Net Price |
| 734262FZ6 | $5,925,000 | 5.00% | 1-Oct-24 | 3.42% | $101.67 | 5.42% | $99.61 |
| 734262GA0 | $6,220,000 | 5.00% | 1-Oct-25 | 3.27% | $103.45 | 5.27% | $99.50 |
| 734262GB8 | $6,530,000 | 5.00% | 1-Oct-26 | 3.18% | $105.30 | 5.18% | $99.51 |
| 734262GC6 | $6,860,000 | 5.00% | 1-Oct-27 | 3.07% | $107.35 | 5.07% | $99.75 |
| 734262GD4 | $7,200,000 | 5.00% | 1-Oct-28 | 3.07% | $109.02 | 5.07% | $99.69 |
| 734262GE2 | $7,560,000 | 5.00% | 1-Oct-29 | 3.06% | $110.69 | 5.06% | $99.69 |
| 734262GF9 | $7,940,000 | 5.00% | 1-Oct-30 | 3.08% | $112.13 | 5.08% | $99.53 |
| 734262GG7 | $8,335,000 | 5.00% | 1-Oct-31 | 3.07% | $113.72 | 5.07% | $99.54 |
| 734262GH5 | $8,750,000 | 5.00% | 1-Oct-32 | 3.10% | $114.94 | 5.10% | $99.29 |
| 734262GJ1 | $9,190,000 | 5.00% | 1-Oct-33 | 3.18% | $115.59 | 5.18% | $98.61 |
| 734262GK8 | $9,650,000 | 5.00% | 1-Oct-34 | 3.25% | $114.94 | 5.25% | $97.93 |
| 734262GL6 | $10,130,000 | 5.00% | 1-Oct-35 | 3.32% | $114.29 | 5.32% | $97.19 |
| 734262GM4 | $10,640,000 | 5.00% | 1-Oct-36 | 3.38% | $113.74 | 5.38% | $96.48 |
| 734262GN2 | $11,170,000 | 5.00% | 1-Oct-37 | 3.48% | $112.83 | 5.48% | $95.35 |
| 734262GP7 | $11,730,000 | 5.00% | 1-Oct-38 | 3.58% | $111.93 | 5.58% | $94.16 |
| 734262GQ5 | $12,315,000 | 5.00% | 1-Oct-39 | 3.67% | $111.12 | 5.67% | $93.01 |
| 734262GR3 | $12,930,000 | 5.00% | 1-Oct-40 | 3.77% | $110.23 | 5.77% | $91.74 |
| 734262GS1 | $13,580,000 | 5.00% | 1-Oct-41 | 3.85% | $109.53 | 5.85% | $90.62 |
| 734262GT9 | $14,255,000 | 5.00% | 1-Oct-42 | 3.93% | $108.83 | 5.93% | $89.49 |
| 734262GU6 | $14,970,000 | 5.00% | 1-Oct-43 | 3.97% | $108.49 | 5.97% | $88.77 |
| 734262GV4 | $86,855,000 | 5.00% | 1-Oct-48 | 4.17% | $106.77 | 6.17% | $85.19 |
| 734262GW2 | $110,850,000 | 5.00% | 1-Oct-53 | 4.25% | $106.09 | 6.25% | $83.16 |
| Total | $393,585,000 |

Annual Cost Estimation
This section considers the annual cost estimation by analyzing the cost of risk vs the cost of prevention. Being an initial investment, the profit materializes in the longer term.
Figure 14 below gives a simple but effective model of how climate risks can be incorporated into a financial model.
Where, is the probability of incurred losses, the probability of a hazard to hit the Port of Houston, is the capital at risk, and the vulnerability. A hazard can be modeled at 20% probability of occurrence in one year, meaning at least one hazard occurs every 5 years. The capital at risk is valued at $1bn. Vulnerability is estimated at 15%.
We can factor this into the following equation:


Financial Risk Analysis
Figure 15 shows Bloomberg data for market risk and credit risk. Generally, market risk is tied to the volatility of interest rates, and credit risk reflects the probability of default of counterparty, in this case the Authority. As of October 1, 2023, it can be seen that the market risk Bloomberg evaluation falls into the category “High Yield 1”, denominated as “HY1”, while the credit risk assessment is “Investment Grade 4”, denominated as “IG4”. Risk spread reflects economic uncertainty and the market risk spread is higher compared to the credit risk spread.
This means that investment in the Bonds is considered riskier from a market risk perspective than from a credit risk perspective. In terms of volatility, the market risk spread is higher than the credit risk spread.

Conclusion
In accordance with recommendations from the Task Force on Financial-Related Disclosures (TCFD), Responsible Alpha makes the following recommendations for the PHA.
In the category of Governance, PHA should plan to disclose the organization’s governance around climate-related risks and opportunities, including the extent of Port Commission’s oversight of climate-related risks and opportunities, and the role of management in assessing and managing climate-related risks and opportunities.
In the category of Strategy, PHA should plan to disclose actual and potential impacts of climate-related risks and opportunities as it relates to business strategy, financial planning and other locations where information is material. These disclosures should include short-, medium- and long-term climate-related risks and opportunities, and an overview of PHA’s resilience strategy in circumstance of 2 degrees C or lower of warming.
In the category of Risk Management, PHA should plan to disclose how it will identify, assess, and manage climate related risks in planning around risk management.
In the category of Metrics and Targets, PHA should plan to disclose metrics and targets they will use to assess and manage climate-related risks and opportunities in terms of Scope 1,2, and 3 (if appropriate) emissions and related risks and how they have performed against said targets.
Climate-related risks are likely to impact revenues, assets and liabilities, expenditures, and capital and financing. As these disclosures become widely required, companies and institutions who already have a plan in place, with a clear path forward, will fare much better than those who wait for regulations.
Appendix: List of Hurricanes and Storms
Table 5: List of 76 Hurricanes and Storms (Data is from the National Hurricane Center. (Accessed October 8, 2023)
| Storm Name | Date Range | Maximum Wind Speed | Minimum Pressure | Maximum Category |
| Name | Date Range | Maximum Wind Speed | Minimum Pressure | Maximum Category |
|---|---|---|---|---|
| Nicholas 2021 | Sep 12, 2021 to Sep 17, 2021 | 65 | 988 | H1 |
| Beta 2020 | Sep 17, 2020 to Sep 25, 2020 | 55 | 993 | TS |
| Imelda 2019 | Sep 17, 2019 to Sep 19, 2019 | 40 | 1003 | TS |
| Bill 2015 | Jun 16, 2015 to Jun 21, 2015 | 50 | 997 | TS |
| Ike 2008 | Sep 01, 2008 to Sep 15, 2008 | 125 | 935 | H4 |
| Edouard 2008 | Aug 03, 2008 to Aug 06, 2008 | 55 | 996 | TS |
| Humberto 2007 | Sep 12, 2007 to Sep 14, 2007 | 80 | 985 | H1 |
| Rita 2005 | Sep 18, 2005 to Sep 26, 2005 | 155 | 895 | H5 |
| Ivan 2004 | Sep 02, 2004 to Sep 24, 2004 | 145 | 910 | H5 |
| Grace 2003 | Aug 30, 2003 to Sep 02, 2003 | 35 | 1007 | TS |
| Allison 2001 | Jun 05, 2001 to Jun 19, 2001 | 50 | 1000 | TS |
| Unnamed 2000 | Sep 08, 2000 to Sep 09, 2000 | 30 | 1008 | TD |
| Frances 1998 | Sep 08, 1998 to Sep 13, 1998 | 55 | 990 | TS |
| Dean 1995 | Jul 28, 1995 to Aug 02, 1995 | 40 | 999 | TS |
| Jerry 1989 | Oct 12, 1989 to Oct 16, 1989 | 75 | 982 | H1 |
| Chantal 1989 | Jul 30, 1989 to Aug 03, 1989 | 70 | 984 | H1 |
| Allison 1989 | Jun 24, 1989 to Jul 01, 1989 | 45 | 999 | TS |
| Unnamed 1987 | Aug 09, 1987 to Aug 17, 1987 | 40 | 1007 | TS |
| Bonnie 1986 | Jun 23, 1986 to Jun 28, 1986 | 75 | 990 | H1 |
| Alicia 1983 | Aug 15, 1983 to Aug 21, 1983 | 100 | 962 | H3 |
| Unnamed 1981 | Jun 03, 1981 to Jun 05, 1981 | 30 | -1 | TD |
| Danielle 1980 | Sep 04, 1980 to Sep 07, 1980 | 50 | 1004 | TS |
| Unnamed 1980 | Jul 17, 1980 to Jul 21, 1980 | 30 | -1 | TD |
| Elena 1979 | Aug 30, 1979 to Sep 02, 1979 | 35 | 1004 | TS |
| Claudette 1979 | Jul 15, 1979 to Jul 29, 1979 | 45 | 997 | TS |
| Unnamed 1977 | Jun 13, 1977 to Jun 14, 1977 | 25 | -1 | TD |
| Carmen 1974 | Aug 29, 1974 to Sep 10, 1974 | 130 | 928 | H4 |
| Unnamed 1974 | Aug 24, 1974 to Aug 26, 1974 | 30 | -1 | TD |
| Unnamed 1974 | Jul 13, 1974 to Jul 17, 1974 | 30 | -1 | TD |
| Unnamed 1973 | Sep 06, 1973 to Sep 12, 1973 | 30 | -1 | TD |
| Delia 1973 | Sep 01, 1973 to Sep 07, 1973 | 60 | 986 | TS |
| Unnamed 1971 | Jul 07, 1971 to Jul 08, 1971 | 25 | -1 | TD |
| Felice 1970 | Sep 12, 1970 to Sep 19, 1970 | 60 | 990 | TS |
| Abby 1964 | Aug 05, 1964 to Aug 08, 1964 | 60 | 1000 | TS |
| Cindy 1963 | Sep 16, 1963 to Sep 20, 1963 | 55 | 996 | TS |
| Debra 1959 | Jul 22, 1959 to Jul 27, 1959 | 75 | 980 | H1 |
| Gerda 1958 | Sep 14, 1958 to Sep 22, 1958 | 50 | 1001 | TS |
| Bertha 1957 | Aug 08, 1957 to Aug 11, 1957 | 55 | 998 | TS |
| Unnamed 1955 | Aug 25, 1955 to Aug 28, 1955 | 45 | 1004 | TS |
| Barbara 1954 | Jul 27, 1954 to Jul 30, 1954 | 50 | 999 | TS |
| Unnamed 1949 | Sep 27, 1949 to Oct 07, 1949 | 95 | 965 | H2 |
| Unnamed 1947 | Aug 18, 1947 to Aug 27, 1947 | 70 | 984 | H1 |
| Unnamed 1946 | Jun 13, 1946 to Jun 16, 1946 | 35 | -1 | TS |
| Unnamed 1945 | Aug 24, 1945 to Aug 29, 1945 | 100 | 963 | H3 |
| Unnamed 1943 | Jul 25, 1943 to Jul 30, 1943 | 90 | 967 | H2 |
| Unnamed 1942 | Aug 17, 1942 to Aug 23, 1942 | 70 | -1 | H1 |
| Unnamed 1941 | Sep 17, 1941 to Sep 27, 1941 | 110 | 985 | H3 |
| Unnamed 1941 | Sep 11, 1941 to Sep 16, 1941 | 50 | 1001 | TS |
| Unnamed 1940 | Sep 18, 1940 to Sep 25, 1940 | 45 | 1004 | TS |
| Unnamed 1940 | Aug 03, 1940 to Aug 10, 1940 | 85 | 972 | H2 |
| Unnamed 1938 | Oct 10, 1938 to Oct 17, 1938 | 50 | 996 | TS |
| Unnamed 1934 | Aug 26, 1934 to Sep 01, 1934 | 70 | 998 | H1 |
| Unnamed 1933 | Jul 14, 1933 to Jul 27, 1933 | 45 | -1 | TS |
| Unnamed 1932 | Aug 12, 1932 to Aug 15, 1932 | 130 | 935 | H4 |
| Unnamed 1921 | Jun 16, 1921 to Jun 26, 1921 | 80 | 980 | H1 |
| Unnamed 1915 | Aug 05, 1915 to Aug 23, 1915 | 125 | 940 | H4 |
| Unnamed 1909 | Jul 13, 1909 to Jul 22, 1909 | 100 | 959 | H3 |
| Unnamed 1908 | Jul 29, 1908 to Aug 03, 1908 | 50 | -1 | TS |
| Unnamed 1900 | Aug 27, 1900 to Sep 15, 1900 | 125 | 936 | H4 |
| Unnamed 1899 | Jun 26, 1899 to Jun 27, 1899 | 35 | -1 | TS |
| Unnamed 1898 | Sep 20, 1898 to Sep 28, 1898 | 50 | -1 | TS |
| Unnamed 1897 | Sep 10, 1897 to Sep 13, 1897 | 75 | -1 | H1 |
| Unnamed 1895 | Oct 02, 1895 to Oct 07, 1895 | 35 | -1 | TS |
| Unnamed 1891 | Jul 03, 1891 to Jul 08, 1891 | 80 | -1 | H1 |
| Unnamed 1888 | Jul 04, 1888 to Jul 06, 1888 | 50 | -1 | TS |
| Unnamed 1888 | Jun 16, 1888 to Jun 18, 1888 | 70 | -1 | H1 |
| Unnamed 1886 | Sep 16, 1886 to Sep 24, 1886 | 85 | -1 | H2 |
Appendix: Plastics Spills Along the Gulf Coast
Nurdles are lentil-sized pellets which are the foundation of most everyday plastic products. Nurdles are heated and formed into the single-use plastic products we use – and throw away – bottles, wrap, film, plastic in clothes and other products. Nurdles are frequently spilled, entering the environment and food chains, e.g., via shellfish and commercial fisheries.
For example, on August 2, 2020, the container ship CMA CGM Bianca (Bloomberg L.P. and Orbis) spilled 750 million nurdles in the Chemical Coast allegedly produced by Dow Chemical when a 40-ft container fell off the vessel’s deck after the vessel became adrift in New Orleans, Louisiana.
Nurdles are packed in 25 kg bags. 990 sacks per container, which equals 24.75 mt, with average weight per nurdle of 0.033g, yielding about 750 million nurdles.
The CMA CGM Bianca flies under the flag of Malta. The ship is owned by CMA CGM. It was built in 2011 by Shanghai Jiangnan Changxing. Skuld provides protection and indemnity insurance for the Bianca. Bianca’s International Maritime Organization number is 9436367. French-based CMA CGM is 74% owned by Lebanese-based Merit Corporation SAL.


“I cried. It was that bad,” said Liz Marchio, National Parks Service science educator. “They were like snowdrifts piled up. Inches deep with the river sloshing around.” For clean-up, CMA CGM the 3rd largest shipping company globally, who reported $31.4 billion in revenue in 2020,xxi hired two men to use leaf blowers to blow the nurdles into the Mississippi River and then try to scoop them out.
Unfortunately, the U.S. Coast Guard and other U.S. regulatory agencies chose to not to penalize or fine CMA CMG or Dow as they do not consider nurdle plastic pollution a “hazardous material” under the U.S. Clean Water Act.
In another example, Diane Wilson, a retired shrimper, sued Formosa Plastics in July 2017, alleging that its Port Comfort plant had illegally discharged thousands of plastic pellets and other pollutants into Lavaca Bay and other nearby waterways along the Chemical Coast. U.S. District Judge Kenneth M. Hoyt ruled against Formosa calling the company a “serial offender“. Texas RioGrande Legal Aid (TRLA) said the $50 million settlement is the largest in U.S. history involving a private citizen’s lawsuit against an industrial polluter under federal clean air and water laws.
Appendix: NOAA Grraphs
The U.S. Climate Resilience Toolkit and Climate Explorer are managed by NOAA’s Climate Program Office and hosted by the National Environmental Modeling and Analysis Center (NEMAC) at the University of North Carolina Asheville.
Built to accompany the U.S. Climate Resilience Toolkit, Climate Explorer graphs projections for two possible futures: one in which humans drastically reduce and stabilize global emissions of heat-trapping gases (labeled Lower emissions, also known as RCP4.5), and one in which we continue increasing emissions through the end of the 21st century (labeled Higher emissions, also known as RCP8.5). Note that only higher emissions projections are available for Alaska. Decision makers can check climate projections based on these two plausible futures and then plan according to their tolerance for risk and the timeframe of their decisions.
For the contiguous United States, the tool also displays observations of climate variables from 1950 to 2013. Users can compare observations to modeled history (results called hindcasts, or projections generated for the past) for the same period. Checking how observations compare to modeled history provides some insight on the models’ collective ability to reproduce past conditions. For temperature-related variables, the range of observations are generally within the envelope of modeled history (hindcasts), indicating model skill in simulating observed conditions. For some variables—especially precipitation-related variables—comparing observations with hindcasts reveals limitations of the models.
Graphs in Climate Explorer show results generated by global climate models for the Coupled Model Intercomparison Project Phase 5 (CMIP5). For the contiguous United States, the climate model data were statistically downscaled using the Localized Constructed Analogs method (LOCA; Pierce et al. 2014). For Alaska, data are from Scenarios Network for Alaska + Arctic Planning (SNAP). For Hawai’i and U.S. territories, data are from global climate model simulations: projections for individual islands were calculated as the average of the three grid points closest to the geographic center of each island.
For the contiguous United States, Hawai’i, and U.S. territories, Climate Explorer shows projections for two potential futures, labeled Lower emissions and Higher emissions; they represent scenarios RCP 4.5 and RCP 8.5, respectively. Projections for Alaska are only for Higher emissions. Learn more about Representative Concentration Pathways (RCPs) »
To produce maps of observed temperatures for 1950 to 2010 for the contiguous United States, we calculated decadal averages for each month of the year using the Livneh observational dataset. For the 2020s to the 2090s, we used weighted averages of all model output to calculate average projected values.
To produce maps of Percent Change in Precipitation for the contiguous United States, we first calculated observed monthly averages of Total Precipitation for the period 1961-1990 (we refer to these values as the 30-year climatology). For January, April, July, and October—the middle month of each season—we calculated 10-year averages of Total Precipitation for the 1950s through the 2000s and subtracted the appropriate monthly climatology from them. We divided the difference by the climatology, and then multiplied the result by 100. For future decades, we used the weighted mean of the 32 models in the LOCA dataset to calculate decadal averages for each of the four representative months and followed the procedure above to calculate percent change relative to the 30-year climatology.
For graphs and maps of Days over or under various thresholds, Heating Degree Days, Cooling Degree Days, Growing Degree Days, Modified Growing Degree Days, all data are presented as average annual values across a decade with the starting year indicated in the time slider.
Days with High-tide Flooding were compiled from tide-gauge data based on locally identified thresholds related to impacts such as flooding of low-lying roads.
Appendix: SLOSH Graphs
The SLOSH (Sea, Lake, and Overland Surges from Hurricanes) model is a numerical model used by NWS to
compute storm surge. Storm surge is defined as the abnormal rise of water generated by a storm, over and above the predicted astronomical tides. Flooding from storm surge depends on many factors, such as the track, intensity, size, and forward speed of the hurricane and the characteristics of the coastline where it comes ashore or passes nearby. For planning purposes, the NHC uses a representative sample of hypothetical storms to estimate the near worst–case scenario of flooding for each hurricane category.
SLOSH employs curvilinear polar, elliptical, and hyperbolic telescoping mesh grids to simulate the storm surge hazard. The spatial coverage for each SLOSH grid ranges from an area the size of a few counties to a few states. The resolution of individual grid cells within each basin ranges from tens to hundreds of meters to a kilometer or more. Sub-grid scale water features and topographic obstructions such as channels, rivers, and cuts and levees, barriers, and roads, respectively, are parameterized to improve the modelled water levels.
The NHC provides two products based on hypothetical hurricanes: MEOWs and MOMs. MEOWs are created by computing the maximum storm surge resulting from up to 100,000 hypothetical storms simulated through each SLOSH grid of varying forward speed, radius of maximum wind, intensity (Categories 1-5), landfall location, tide level, and storm direction. A MEOW product is created for each combination of category, forward speed, storm direction, and tide level. SLOSH products exclude Category 5 storms north of the NC/VA border. For each storm combination, parallel storms make landfall in 5-to-10-mile increments along the coast within the SLOSH grid, and the maximum storm surge footprint from each simulation is composited, retaining the maximum height of storm surge in a given basin grid cell. These are called MEOWs and no single hurricane will produce the regional flooding depicted in the MEOWs. SLOSH model MOMs are an ensemble product of maximum storm surge heights. SLOSH MOMs are created for each storm category by retaining the maximum storm surge value in each grid cell for all the MEOWs, regardless of the forward speed, storm trajectory, or landfall location. SLOSH MOMs are available for mean tide and high tide scenarios and represent the near worst–case scenario of flooding under ideal storm conditions. A high tide initial water level was used for the storm surge hazard maps.
This product uses the expertise of the NHC Storm Surge Unit to merge the operational SLOSH grids to build a seamless map of storm surge hazard scenarios using the MOM product. Each individual SLOSH grid for the Category 1-5 MOMs are merged into a single, seamless grid. The seamless grid is then resampled, interpolated, and processed with a DEM (Digital Elevation Model, i.e. topography) to compute the storm surge hazard above ground for each hurricane category. The SLOSH MOM storm surge hazard data used to create these maps are constrained by the extent of the SLOSH grids and users should be aware that risk due to storm surge flooding could extend beyond the areas depicted in these maps.


